The Story
Picture two neighbors, same storm, same damage, same insurer, both with a roof that needs replacing at a cost of, say, twenty-two thousand dollars.
One of them ends up substantially out of pocket. The other doesn't.
Neither of them did anything wrong after the storm. The difference was decided years earlier, in a paragraph of the policy neither had read.
The Mechanism
There are two ways an insurance policy can value a roof, and the gap between them is the single largest hidden number in Texas homeownership.
REPLACEMENT COST VALUE (RCV) pays what it costs to replace the roof today, subject to your deductible.
ACTUAL CASH VALUE (ACV) pays replacement cost minus depreciation for age and wear. A fifteen-year-old roof on a twenty-year expected life has lost most of its value on paper — so the payment reflects a fraction of what the work actually costs. The rest is yours.
For years, RCV was the default in Texas. It is increasingly not. As hail losses mounted, carriers moved large numbers of policies onto ACV roof settlement, or onto a "roof payment schedule" endorsement that steps the payout down by a set percentage for every year of roof age.
Here is what matters: this is usually not a change you were asked about. It arrives inside a renewal packet, as an endorsement, in a stack of paper that looks like the last stack of paper.
The Opportunity That Comes To You
Your declarations page is sitting in your email or a drawer right now, and reading it is free.
Find these four things:
- Does it say Replacement Cost or Actual Cash Value for the roof specifically? The dwelling can be RCV while the roof alone is ACV. That split is common and it surprises people.
- Is there a roof payment schedule or roof surfacing endorsement attached? If so, find the table. It will show payout as a percentage against roof age.
- What is your wind and hail deductible, and is it a flat dollar amount or a percentage? (That's the whole of the next issue.)
- What is your roof's age as your insurer has it recorded?
You are allowed to call your agent and ask all four. It costs a phone call. It is also the conversation where you find out whether RCV is still available to you and what it would cost — sometimes materially less than people assume, sometimes not available at all for an older roof. Either answer is worth having before a storm rather than after.
The Opportunity You Create
Notice what every one of those levers turns on: the age and documented condition of the roof.
Age drives the depreciation schedule. Condition drives whether damage reads as storm-related or as wear. And in the absence of any independent record, both of those get established after the fact, by whoever is looking at the roof at the time, from the evidence available then.
You cannot make your roof younger. You can absolutely make its condition a matter of record rather than a matter of argument — and you can do it on a quiet day, at no cost, years before it matters.
That is the created opportunity. It's not glamorous. It's a dated file.
Next issue: the deductible math that turns a twenty-two thousand dollar roof into a claim that isn't worth filing.
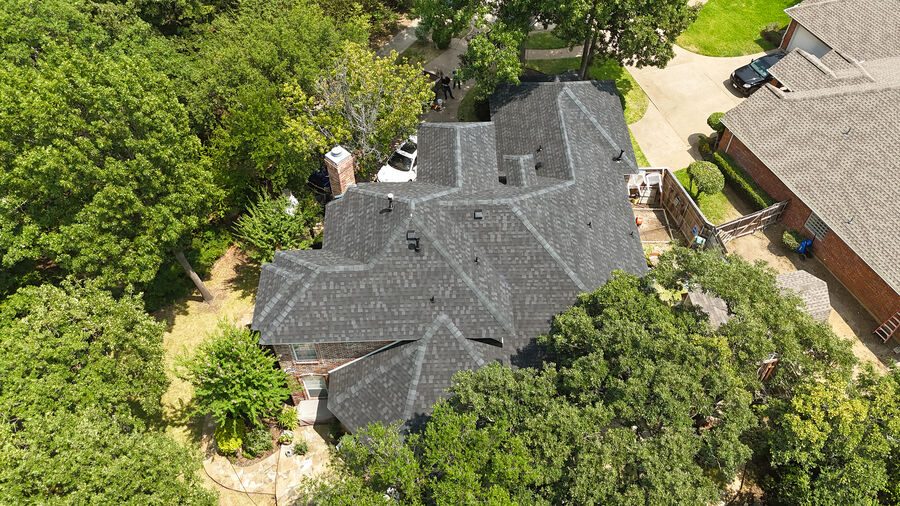
So: free HomFax inspection at your home. Forty-five minutes. Photo survey of every slope and elevation, timestamped and geotagged, the soft-metal evidence that corroborates hail impact, your roof's condition and estimated remaining serviceable life, and the NOAA hail history for your ZIP including June 1, 2025.
Written up, emailed, yours to keep permanently. Free, and no obligation of any kind — if the roof is in good shape the report says so, and you have a dated baseline for whatever comes next.
Book: /book Or reply with a day.