Two companies rated your home's risk. They didn't agree.
Property risk scores are presented as facts. When researchers got two of the companies that produce them to compare notes, their rankings of the same houses barely lined up.
Insurance, storm damage, claims, contractors and cost — written plainly, for the people who have to live with the answers. Everything checkable against a source.
An isolated cell formed near Rhome at half past five and was gone by seven. It left quarter-to-ping-pong hail through Haslet and Keller, a commercial roof on the ground in Watauga, and a gap in the instrument record where the strongest wind probably blew.
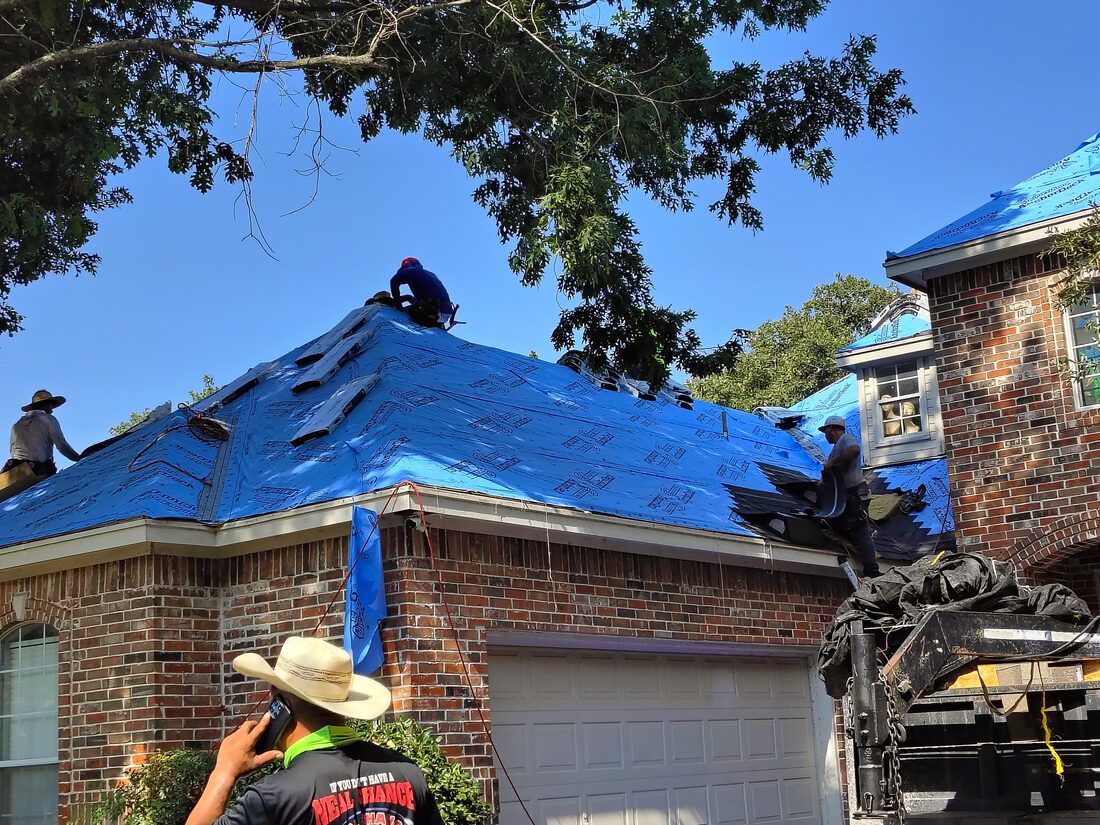
Nearly every bad result after a storm traces back to one of these. The Journal works through them in the order a homeowner meets them.
Deductibles, replacement cost versus actual cash value, depreciation, exclusions, code upgrades — and what you may still owe.
What your homeowners policy really means, before and after a loss Your roof has two values; your policy already picked one The 2% you didn't know you'd agreed toHail bruising, lifted and creased shingles, flashing, vents, gutters, soft metals. Why a visible leak is a late symptom, not an early one.
Ninety minutes over north Tarrant County: what the August 26 storm actually did Two companies rated your home's risk. They didn't agree. How to find storm damage before it finds you The ninety-minute annual reviewPhotograph everything, prevent further damage, keep receipts, and preserve evidence before permanent repairs begin.
In preparationInsurance, references, warranties, written scope, payment terms — and why nobody may lawfully promise to absorb your deductible.
How to make a storm chaser leave on their ownDeductible payment plans, financing, uncovered upgrades, depreciation, and your true out-of-pocket responsibility.
In preparationProperty risk scores are presented as facts. When researchers got two of the companies that produce them to compare notes, their rankings of the same houses barely lined up.
It is the most expensive document most people own and the least read. Here is what is actually inside it, and what it will ask of you on the worst day of your year.
Two identical houses, one filed a piece of paper, and nine hundred dollars a year separates them.
The envelope from the appraisal district is an opinion, not a verdict — and it has a deadline printed on it.
Replacement cost or actual cash value. Your policy already chose, and the gap is the largest hidden number in Texas homeownership.
Most homeowners can recall a deductible figure. Many are recalling the wrong one.
Each alert states a fact, cites the statute where one applies, and links to a source you can check yourself.
Which means checking a contractor is your job. Here is how to do it with public records, in about fifteen minutes, before you sign anything.
Reading about evidence is one thing; having some is another. Forty-five minutes produces a timestamped, geotagged photo survey of your roof matched to the NOAA hail record for your ZIP — written up as a report you keep.
Book a free inspection (844) 466-3290
No cost, no obligation, and no follow-up call unless you ask.
New articles and consumer alerts. A few a year, not a few a week.
One-click unsubscribe in every email, honoured immediately. We don't sell or share your address.